
The loan the bank said you couldn't have.
Self-employed, running a business, or carrying something on your file that makes a bank nervous? That's most of who I help. One conversation, more than twenty-five lenders, and a straight answer about where you really stand.
What brings you here today?
 Google Reviews
Home loans
First home, next home, or building. I compare the whole panel — including the lenders who will look beyond one year of tax returns.
See how it worksInvestment loans
Your first investment or your fifth. Structured so the next purchase is still possible after this one settles.
See how it worksRefinancing
Coming off a fixed rate, or paying the loyalty tax? I'll tell you whether moving is worth it — and when it isn't.
See how it worksMore than 25 lenders, not one bank's opinion
 ANZ
 Westpac
 St.George
 Macquarie
 ING
 Suncorp
 Bank of Queensland
 AMP Bank
 Bank of Melbourne
 ME Bank
 Adelaide Bank
 UBank
 Pepper Money
 Liberty
 La Trobe Financial
 Resimac
 Bluestone
 Thinktank
Panel accessed through Finsure. Lender appetite changes constantly — part of my job is knowing who is saying yes this month.
Fifteen minutes, and you'll know where you stand
No credit check, no obligation, and no cost. If the answer is "not yet", I'll tell you that too — and exactly what to fix first.
Residential and commercial, under one roof
Most brokers do houses. Fewer do trucks, excavators and warehouses as well. When the same person handles both, the business lending gets structured so it doesn't quietly cost you the home loan.
Home loans
Buying your first or your next. Full-doc, alt-doc, and lenders who accept twelve months of returns.
Find out moreRefinancing
Cut the rate, release equity, or roll business and personal debt into one sensible structure.
Find out moreInvestment loans
Equity release, interest-only, portfolio structuring and the serviceability maths that decides your ceiling.
Find out moreConstruction loans
House and land, knockdown rebuild, or a major renovation. Progress draws managed so the builder gets paid on time.
Find out moreCommercial property
Buy the warehouse or shop you're currently renting. Owner-occupied, investment and SMSF structures.
Find out moreTruck & equipment
Prime movers, trailers, excavators, fit-outs and plant. Chattel mortgage or lease, priced against the whole market.
Find out moreBusiness finance
Working capital, cash-flow facilities, overdrafts and acquisition funding for Western Sydney SMEs.
Find out moreSpecialist lending
Defaults, ATO arrears, discharged bankruptcy, short-term private funding. Honest odds, no theatre.
Find out moreA bank has one credit policy. I have more than twenty-five.
When a bank declines you, that isn't a verdict on your finances. It's a verdict on how well you fit that one bank's rules on that one day. Twenty-one years in lending — including years inside the majors — means I can usually tell you on the first call which lenders will say yes, and what needs to change for the rest.
-
You deal with me. Start to finish.
Not a call centre, not a junior, not a different name on every email. The person you meet is the person who structures your file, argues it with the assessor, and answers the phone at seven in the evening.
-
I read a BAS the way a credit assessor does.
Add-backs, retained profit, depreciation, ATO payment plans, one year of returns instead of two. Self-employed income is where most applications quietly die, and it's where most of my approvals come from.
-
One broker for the house and the business.
The home loan, the warehouse, the excavator and the prime mover — planned together. How you fund the business decides what you can borrow for the house, and almost nobody tells you that before it's too late.
-
No cost to you on most loans.
The lender pays me a commission when your loan settles. Where a fee does apply — some commercial and specialist deals — you get the exact amount in writing before you commit to anything.
What clients have said on Google
The most helpful and fastest brokers in Sydney! What can we say, you guys [took] all the [headache] out of the whole process! Ensured timely delivery on all our loan paperwork and helped us all the way to settlement! Thank you, we are so happy with your service and we would recommend you guys to anyone!

Simply the best broker in Sydney! Alen, you helped us so many [times] with our properties and got us the best rate available! You made the process so easy and simple! Thanks, would recommend to everyone!
The BEST BROKER in SYDNEY! That is all!
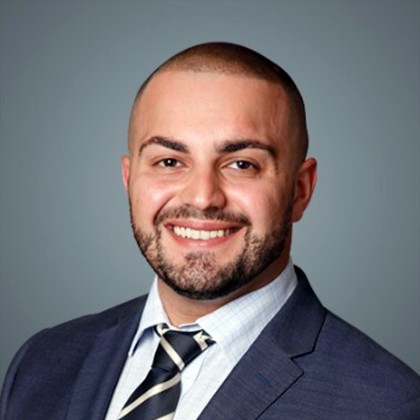
Alen Slewa
Principal broker · 21 years in lending Credit Representative Number 496223 · Finsure, Australian Credit Licence 384704 · Wetherill Park, NSWI started on the other side of the desk, inside the major banks, across both residential and commercial lending. I spent those years watching perfectly good applications get declined for reasons the customer was never told — a policy quirk, a document presented the wrong way, income that was real but didn't fit the template.
Twenty-one years in lending later, I run Proficient Finance Group from Wetherill Park, working with families and business owners across Western Sydney. I keep the practice small on purpose. It means I take fewer files than a franchise office, and it means nobody hands your loan to someone else halfway through.
A rough idea, in ten seconds
Move the sliders for a ballpark. A real assessment looks at your liabilities, living expenses, credit file and each lender's own servicing rules — and the gap between this number and the right number is often large, in both directions.
If you're self-employed, the gap is usually largest of all. That's the conversation worth having.
Get the real numberIndicative only. Not an offer of credit, a pre-approval, or a guarantee that finance will be provided. Lending criteria, fees and charges apply.
The questions people are too polite to ask
If yours isn't here, call and ask it. I'd rather spend ten minutes on the phone than have you not apply.
Ask Alen directlyWhat does it cost to use a broker?
Nothing, on almost every residential loan. The lender pays a commission when your loan settles — an upfront amount, then a smaller trail across the life of the loan. You don't pay more by coming through me than you would by walking into the branch yourself.
Some commercial and specialist deals do carry a fee. Where that applies, you get the exact figure in writing before you commit to anything, and you'll know why it applies.
Will talking to you affect my credit score?
No. Nothing touches your credit file until you've chosen a lender and told me to lodge. We can talk through your situation, run the numbers and shortlist lenders without a single enquiry being recorded.
What does damage a file is shopping around yourself, bank by bank — each formal application leaves a mark, and a cluster of them in a short window makes the next lender nervous.
I'm self-employed with one year of returns. Am I wasting your time?
No, and this is a large part of what I do. Several lenders on my panel will write a loan on twelve months of returns. A few will work from BAS statements, business bank statements or an accountant's declaration instead — these are usually called low-doc or alt-doc products.
The rate is typically a little higher than a full-doc loan, and the deposit requirement can be larger. In many cases the loan can be refinanced onto sharper pricing once you have a second year of returns behind you, which is something I'll flag at the start rather than after settlement.
A bank has already declined me. What now?
Tell me which bank, and if you know it, why. That's genuinely useful — it narrows down which of the other lenders will look at the same file differently, because their policies differ far more than people expect.
Sometimes the answer is a different lender today. Sometimes it's the same lender in six months, after we fix one specific thing. I'll tell you which, and I'd rather tell you to wait than put you through an application that's going to fail.
What costs should I budget for beyond the deposit?
In New South Wales the main one is transfer duty, calculated on a sliding scale based on the property value. First home buyers may be eligible for an exemption or concession depending on the price and the property type, and the thresholds change from time to time, so it's worth checking the current Revenue NSW figures rather than relying on what a friend paid.
Beyond that, budget for conveyancing, building and pest inspections, loan application or settlement fees where they apply, mortgage registration and title searches, and moving costs. If your deposit is under 20 per cent, Lenders Mortgage Insurance may also apply and can be a significant amount. I'll give you a written estimate for your specific purchase before you start looking seriously.
How long does approval take?
For a straightforward application with a major lender, pre-approval usually comes back within a few business days. Formal approval through to settlement commonly runs four to six weeks, though it can stretch during busy periods or where the file is more complex.
Self-employed, construction and commercial applications generally take longer because there's more to assess. The single biggest factor in speed is whether the documents are complete and correctly presented at lodgement, which is the part I control.
What documents will I need?
If you're salaried: recent payslips, your most recent notice of assessment or tax return, three to six months of bank statements, identification, evidence of your deposit, and details of existing debts.
If you're self-employed: two years of personal and business tax returns where available, financial statements, business bank statements, and often an accountant's letter. For purchases, add the contract of sale. I'll send you a checklist built for your situation and the specific lender, rather than a generic list of everything imaginable.
Should I fix my rate or stay variable?
It depends on how much certainty you need and how much flexibility you'd be giving up. Fixed rates lock in your repayment for a set period, which helps if your budget is tight or your income is variable. Variable rates move with the market and usually come with offset accounts and unrestricted extra repayments.
Splitting the loan — part fixed, part variable — is a common middle path. I'm not going to tell you which way rates will move, because nobody knows. I will tell you what each option costs you if you're wrong.
Can you handle both my home loan and my business finance?
Yes, and I'd encourage it. The two are connected whether or not anyone tells you. A chattel mortgage on a new truck affects your serviceability for a home loan. A director's guarantee on a commercial facility shows up in your personal assessment. Debt structured in the wrong entity can cost you the house you were saving for.
When the same person sees both sides, the sequencing can be planned deliberately — which purchase goes first, through which lender, in which name.
Latest from Proficient Finance
Coming off a fixed rate in 2026: what to do first
The two numbers to find before anything else, why breaking a fixed loan may cost less than you think, and a timeline for the six months before expiry.
Asset financeFinancing a prime mover without sinking your home loan
What the instant asset write-off actually covers, the difference between a balloon and a residual, and why truck finance hits a home loan twice.
Self-employedBuying a home when your income comes from an ABN
Why a profitable business can still produce a small assessed income, what lenders actually ask for, and the add-backs that change the answer.
Tell me your situation. I'll tell you where you stand.
Pick a time that suits you, or just call — I answer my own phone. Evenings and weekends are usually fine.